Believe In The BestMount Pleasant Brampton Real Estate Guide (2026)Prices, GO Transit access, and buyer trends in Brampton West's transit-oriented village communityGO Transit Access Modern Homes

Dated: August 8 2026
Views: 75
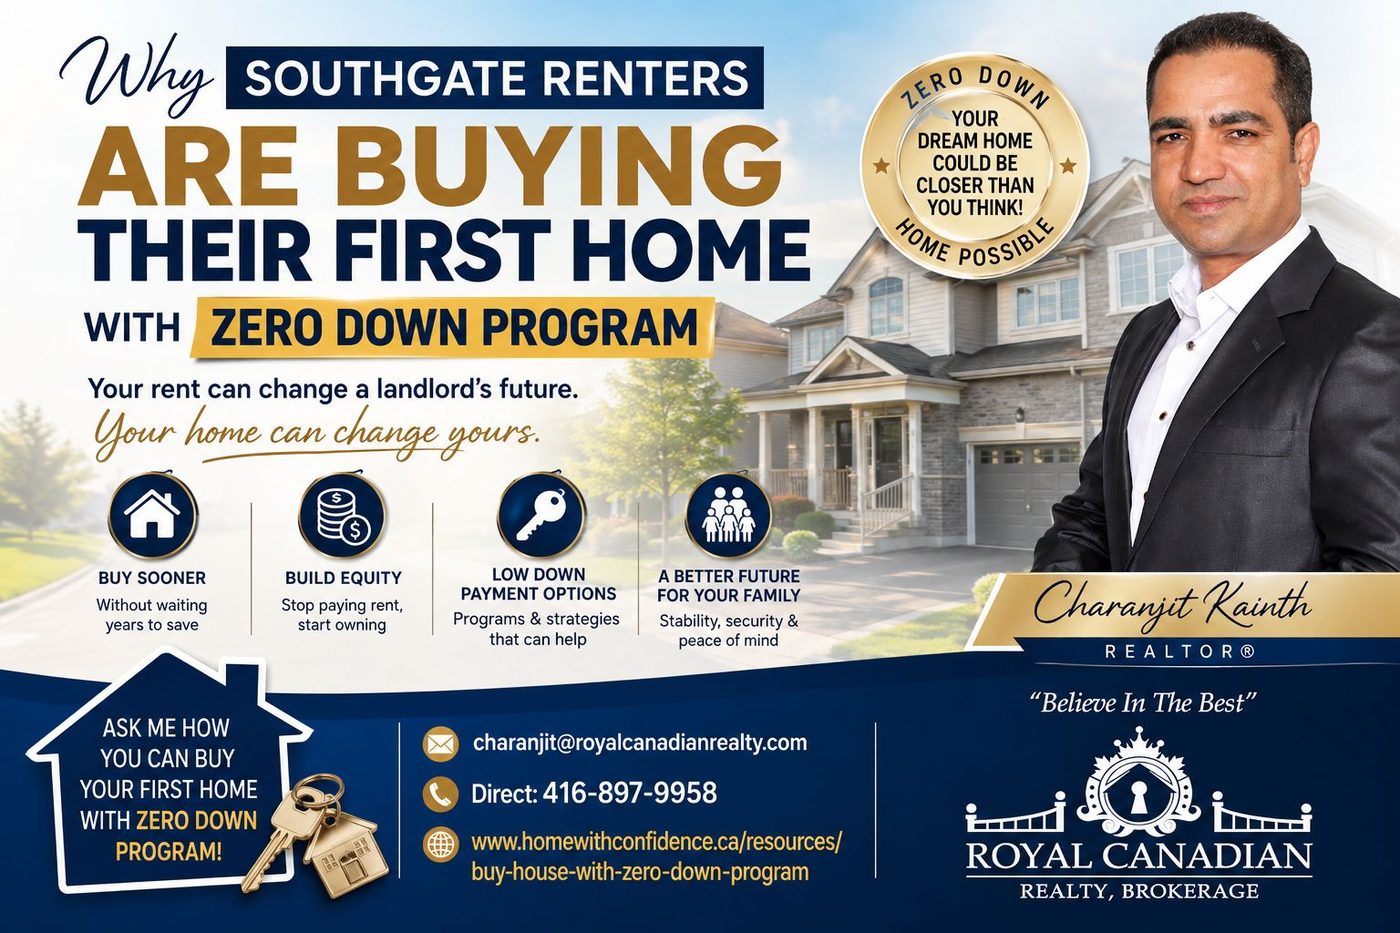
If you rent in Southgate, Brampton, you have probably asked yourself a frustrating question: “How am I ever going to save enough for a down payment while paying rent?”
You are not alone. Many renters have stable income, decent credit, and a strong payment history. They can often afford monthly housing costs similar to a mortgage. But one obstacle keeps getting in the way — the down payment.
That is why more Southgate renters are starting to explore alternative strategies, including what is often referred to as a “Zero Down Program.”
Let’s clear this up first. There is no program in Canada that simply allows buyers to purchase a home with no financial responsibility. All insured mortgages require a minimum down payment:
However, some lenders and mortgage insurers allow borrowed funds to be used toward that required down payment — if the borrower qualifies. This is where the term “Zero Down” comes from.
It does not mean no cost. It means the down payment may come from an approved financing source instead of savings.
Southgate is an established Brampton community near Bramalea Road and Steeles Avenue East, with schools, parks, and shopping nearby. Many renters already work in the area, have kids in local schools, know the neighbourhood well, and want to stay long term.
So the goal is not relocation. It is transition: from renting in Southgate to owning in Southgate.
When renters say they “can’t afford to buy,” they are usually referring to three separate issues:
In many cases, the biggest blocker is not income — it is the ability to save tens of thousands of dollars while paying rent.
Consider a $600,000 purchase:
For someone paying $2,500–$3,000 in rent, saving $35,000 can take years. That delay is exactly why some buyers explore alternative financing options.
This is not about rushing into ownership. The better question is: “Does buying make sense for my situation right now?”
Neither is universally better. But if you plan to stay in Southgate long term, the comparison is worth analyzing.
A common misconception is that you need 20% down to buy. In reality, insured mortgages allow less than 20% down, though mortgage default insurance is required in those cases and qualification standards still apply.
High savings are helpful — but not always mandatory to get started.
Beyond down-payment strategies, buyers may have access to:
A smart strategy often combines multiple tools.
It is about time. Saving a large down payment can take years. A qualified buyer using an approved strategy may be able to enter the market sooner instead of waiting. But this only works if you qualify, you can afford the total monthly cost, and the numbers make sense long term.
Borrowed down payment means additional debt. Your real monthly obligation could include:
A Zero Down strategy should solve a barrier — not create a financial problem.
This type of strategy may suit buyers who have:
It is not for everyone — and that is okay.
Assuming they cannot buy without ever checking. Many people think, “I don’t have $50,000, so I’m not ready.” But qualification depends on much more than savings: income, credit, debt ratios, down payment source, and property type. The only way to know is to run the numbers.
If you already live in Southgate, you have an advantage — you understand the area better than most buyers. Instead of searching all over Brampton, start with: “What could I realistically own here?” That clarity makes the process far more practical.
It does not mean automatic approval. It does not mean free money. It does not eliminate closing costs. It does not remove mortgage insurance requirements. It does not make an unaffordable home affordable. It is simply one possible financing approach.
Before browsing listings, get a proper mortgage assessment. That tells you what you qualify for, what your real budget is, and whether a Zero Down strategy is even an option. From there, everything becomes clearer.
Planning your total home buying budget in Peel Region? Explore our master
Deciding between an established Bramalea neighborhood and a newer transit hub like Mount Pleasant? Read our head-to-head comparison on buying in
Your Local Buyer’s Real Estate Agent in Brampton and MississaugaBuying a home is more than just a transaction — it’s a major life decision. As a Realtor focused on helping home buyer....
Believe In The BestMount Pleasant Brampton Real Estate Guide (2026)Prices, GO Transit access, and buyer trends in Brampton West's transit-oriented village communityGO Transit Access Modern Homes
Tired of Renting in Bramalea? How to Buy Your First Home Near Bramalea City Centre with Zero Down (2026 Guide)A practical roadmap for renters near Bramalea City Centre, Central Park Drive, Clark
Helping qualified Queen Street Corridor renters explore a path from renting to homeownership in Brampton through Royal Canadian Realty's Zero Down Homeownership Program.Brampton First-Time Buyers
Royal Canadian Realty, Brokerage • "Believe In The Best"Brampton Buyer Guide · 2026First-Time Buyer Guide to Heart Lake, Brampton (2026): Prices, Schools & Top
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Mississauga may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 24, 2026 12:48 PM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Mississauga may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 24, 2026 5:35 AM UTC
Show More...
